Investment / Editorial content
Off-plan or ready property in Dubai: which fits your investment?
Compare off-plan and completed property in Dubai: payment, handover, financing, costs, liquidity and checks for non-resident buyers.
At a glance
- Off-plan and ready property differ in availability and capital commitments; neither guarantees a return.
- Payment plans, financing and resale terms require confirmation in the contract and with the institutions involved.
- Project, escrow, provisional registration, title and inspection play different roles in due diligence.
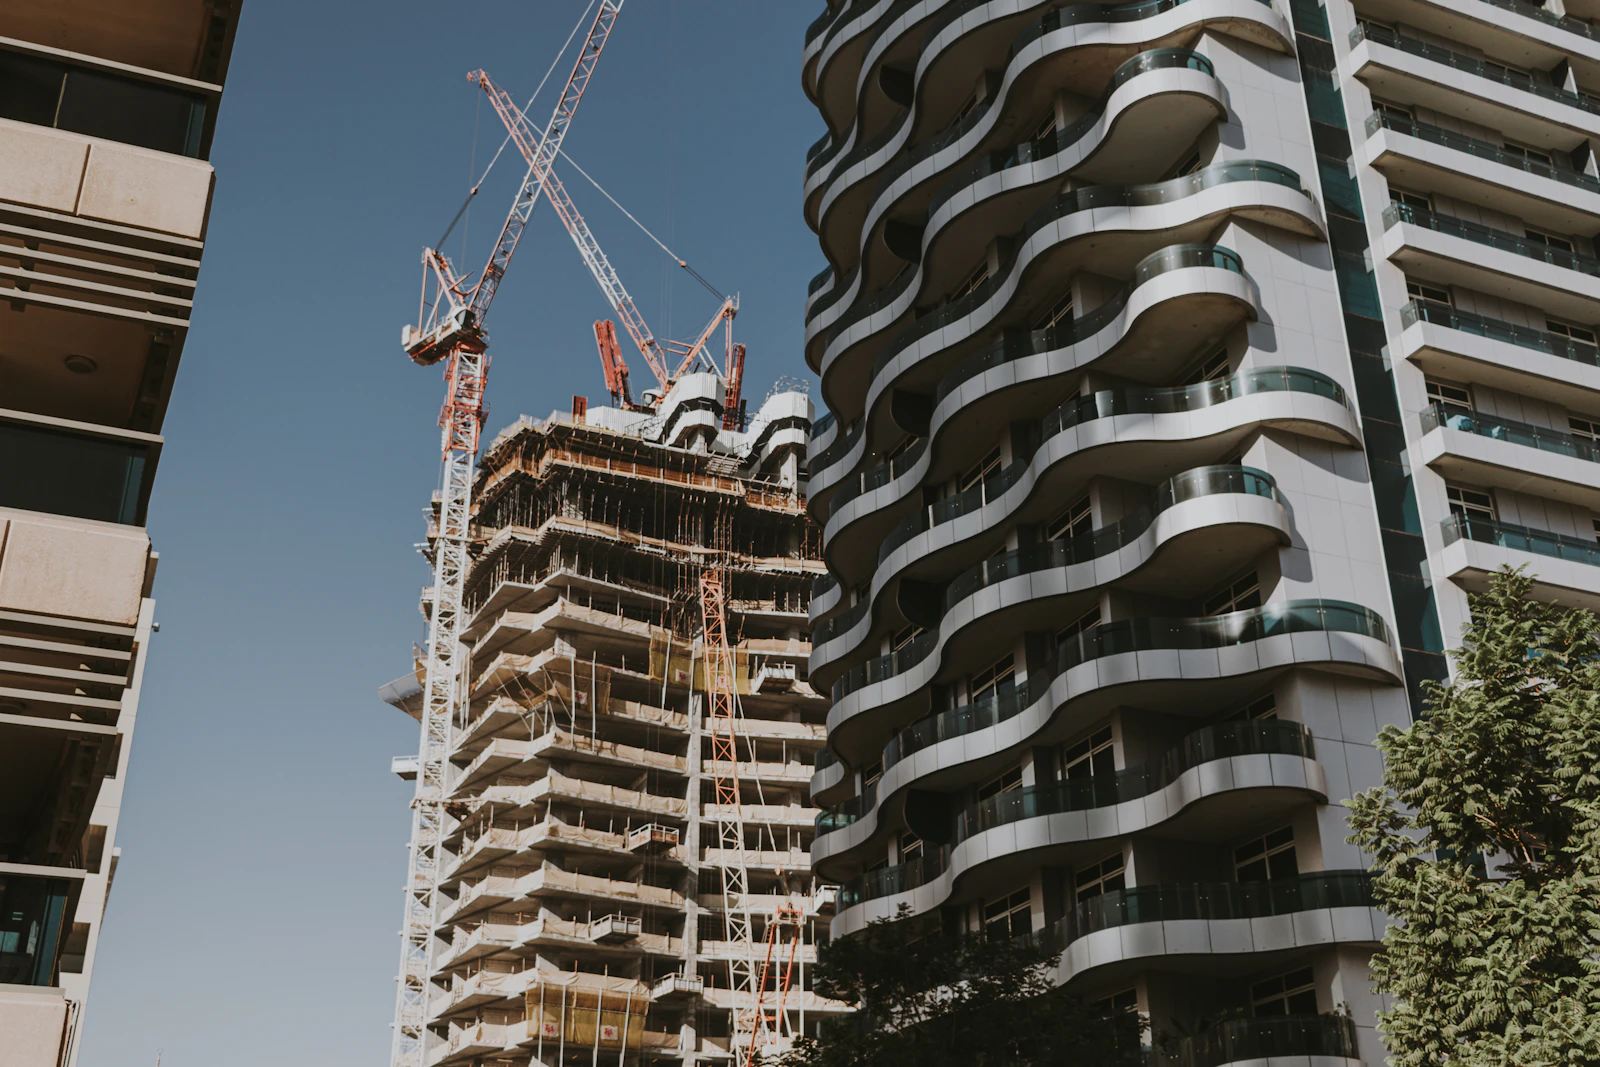
Archive photograph of Dubai: construction and a residential building. Kate Trysh / Unsplash.
At a glance: start with timing, not a promise
Off-plan means buying before a property is completed; a ready property is a completed unit. For an investor, the central difference is when capital is committed, when the property can be used and which uncertainties must be absorbed. An instalment plan can spread cash outflows without reducing the overall commitment. A completed unit can be inspected, but does not ensure immediate occupancy or income.
Neither option is superior in every scenario. Compare actual units and contracts against your objective, budget, timeframe and exit needs. This is an editorial assessment: procedures attributed to DLD are official references, while payment, lending and resale depend on the transaction terms.
Off-plan and ready property, side by side
| Criterion | Off-plan | Ready property |
|---|---|---|
| Payment | Instalments and balance follow the contract; examine handover concentration. | Payment and transfer timetable to agree; any loan depends on approval. |
| Availability | Use depends on completion, handover and occupancy conditions. | Completed unit; occupancy depends on transfer, condition and any existing tenancy. |
| Risks | Construction, delay, specifications and future commitments. | Defects, maintenance, occupancy, outstanding charges and documentation. |
| Financing | A developer payment plan is not an approved bank loan. | Lending depends on the buyer, valuation and lender criteria. |
| Liquidity | Assignment and resale depend on contract, registration and demand. | Resale depends on price, demand, documents and any encumbrances. |
| Costs | Registration and transaction charges; project future ownership expenses. | Acquisition costs plus the unit’s current charges and maintenance. |
| Essential checks | Project, developer, escrow, contract and provisional registration. | Title, seller, unit, occupancy and transfer conditions. |
Payment: the timetable matters as much as the price
For off-plan, turn the marketing payment plan into a schedule of commitments: reservation, construction-stage instalments, the handover balance and any later instalments only where the contract provides for them. Identify which obligations depend on dates or construction milestones and how delays affect them. Do not assume a construction delay automatically suspends payment.
For a completed unit, coordinate available funds, transfer and any mortgage settlement or financing steps. Compare the capital needed to complete with a reserve for expenses and unexpected costs. For funds held in reais or another currency, exchange movements and remittance charges can change the funding burden under either approach.
Availability: completion does not mean immediate income
For a property under construction, examine the contractual timetable, handover conditions, specifications and delay provisions. A marketing completion date is not a guarantee. Consider how you would fund a longer period without use or rent, without relying on appreciation to meet instalments.
For a completed unit, establish whether it is vacant or tenanted, examine any existing tenancy and confirm when possession can be taken. Inspection, repairs, furnishing and preparation for letting may require time and money. Completion does not mean a property is available to occupy or earn rent on the purchase date.
Financing: confirm before committing
A developer payment plan schedules contractual obligations; it is not approval for a bank loan. For both ready and off-plan property, confirm that the lender accepts the unit and borrower profile. Deposit, valuation, income, currency, residency, term and borrowing costs vary; there is no universal non-resident lending offer here.
If your strategy depends on a future loan at handover, treat approval as an uncertainty to resolve rather than guaranteed funding. Assess a valuation below the purchase price or terms different from those expected, with guidance from the financial institution before committing.
Acquisition and ownership costs: separate budgets
Request a transaction-specific breakdown: registration, documents, services, brokerage and any financing charges. Do not assume a completed-property transfer schedule applies unchanged to an initial off-plan sale, or that a marketing offer removes unmentioned costs. Document who bears each charge.
During ownership and at the relevant stage of possession, service charges, maintenance, applicable insurance, management and vacancy affect results. For a completed property, request current unit and building information. For off-plan, distinguish estimated charges from confirmed amounts; do not project net income using zero expenses.
See official charges and the AED 1 million purchase illustration in the buying guide
Liquidity and exit: both contract and market must allow it
Before buying off-plan with a pre-handover resale in mind, check assignment terms, consents, required payments and charges in the applicable documents. Do not treat a minimum paid percentage as a universal rule: obtain the project-specific conditions and confirm the registration procedure. A contractual exit route does not ensure a buyer will be found.
With ready property, access for viewing and an operating history can help assessment, but price, competing supply, occupancy and documents still influence a sale. Compare exit scenarios that do not depend on a quick resale or price growth. Selling expenses also belong in the decision.
What to check: project, registration and unit
DLD’s Register Project service enables the developer to register a development and open its off-plan escrow account. Initial-sale registration takes place in the provisional register through Oqood and issues a provisional electronic certificate. Project registration and registration of the purchase are distinct steps; a provisional certificate should not be confused with the title of a completed unit.
DLD: project registration and opening an escrow account
DLD: initial-sale registration through Oqood
Use the development’s exact details to check progress. DLD’s enquiry reports completion percentage and project details; it is not a guarantee of timing or profitability. Verify the beneficiary and payment details through a trusted channel. DLD’s escrow guidance explains how funds are handled without making the mechanism a promise of return or freedom from risk.
Check project status and progress with DLD
DLD guidance on escrow and ownership
For ready property, check the seller’s identity, title details, occupancy, charges and transfer conditions, alongside a suitable physical inspection. DLD’s title-verification service checks the validity of the issued document; it does not replace an assessment of encumbrances, contract terms, condition or outstanding obligations. Resolve legal questions with qualified professionals.
Verify title-deed validity with DLD
Making the decision as a non-resident buyer
First confirm that the unit is eligible for foreign ownership in a permitted area. Then compare your intended use date with actual availability and organise identification, representation where needed and remittances. Being outside the UAE does not lessen the importance of inspection, contract review or independent verification; establish who follows each stage and how documents will be checked.
If use is needed soon, an available ready unit may reduce reliance on construction without removing other risks. If your horizon allows time and future commitments, off-plan can enter the comparison where the project, contract and finances align. These are not universal recommendations: an unsuitable unit does not become suitable merely because it is ready or off-plan.
Connect the choice to a Dubai property investment strategy
Criteria for selecting Dubai properties and apartments
Explore the projects presented and confirm current terms
Editorial perspective and sources
Sara Cristina, Partner & Head of Operations at Laren, frames the comparison around location, developer, price, demand, cash flow and exit strategy. The purchase format is one part of that assessment, not a performance promise. Official sources checked on 29 October 2026 are linked to the checks above; financing, timing, assignment and commercial terms must be confirmed in the transaction documents. This is information, not individual financial, legal or tax advice.